What is the scope and industry significance of the Family Offices Market?
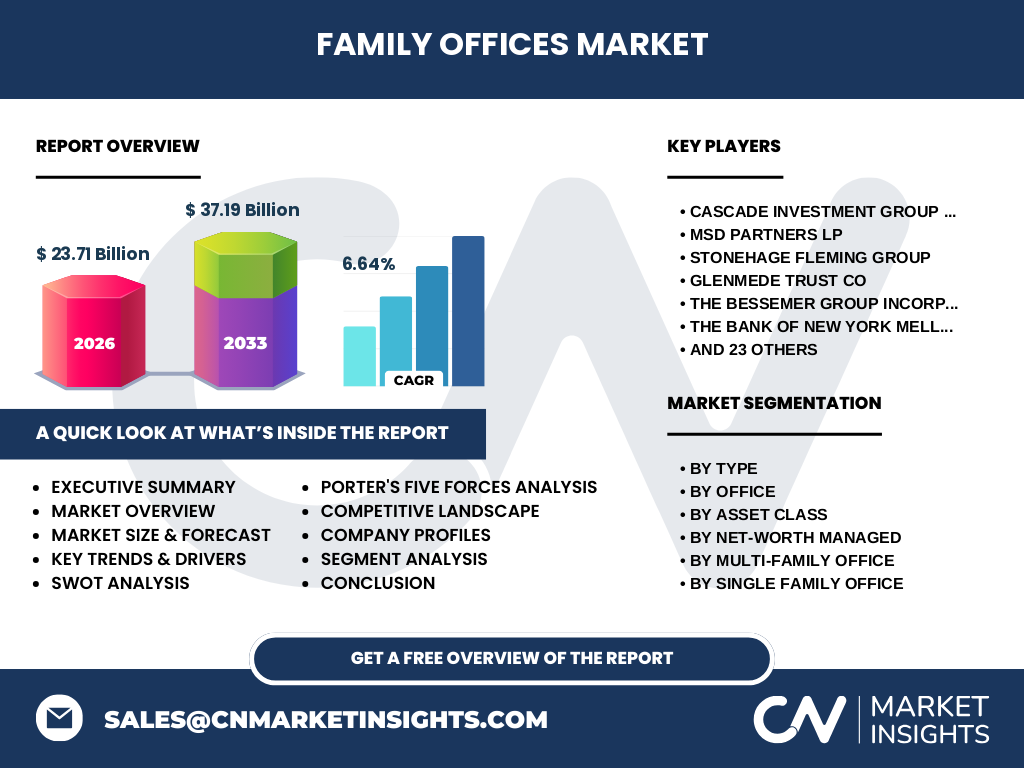
Our analysis indicates that the Family Offices Market achieves a valuation of 23.71 Billion in 2026, serving as the foundational wealth preservation and succession architecture for ultra-high-net-worth entities. This specialized ecosystem coordinates private equity allocations, philanthropy, and regulatory compliance across global jurisdictions, distinguishing itself from standard retail wealth management.
Key market drivers, restraints, challenges, and opportunities shaping the Family Offices Market
The market is driven by generational wealth transfer and surging allocations toward alternative assets. However, stringent regulatory compliance mandated by bodies like the SEC creates operational headwinds. Opportunities lie in adopting digital wealth platforms to streamline multi-generational reporting and cross-border tax management.
Emerging trends and growth patterns in the Family Offices Market
The sector experiences a profound pivot toward direct venture investments and sustainable impact investing. Specialized firms like Emerson Collective LLC and Bezos Expeditions LLC pioneer tech-forward deployment strategies, outperforming traditional passive equity holds and reshaping portfolio diversification models.
COVID-19 impact analysis and the recovery trajectory
The pandemic acted as a powerful catalyst for modernization, compelling traditional offices to adopt cloud-based security and digital portfolio monitoring. Recovery has been robust, accelerated by market volatility that created distressed asset acquisition windows for liquid single-family offices.
Competitive landscape and strategic market concentration
Market concentration features a mix of elite independent entities and massive institutional platforms. Industry leaders such as Stonehage Fleming Group and The Pictet Group dominate through bespoke global fiduciary services, whereas institutions like UBS Group AG leverage institutional banking networks to capture multi-family mandates.
Executive summary of the Family Offices Market
Our research confirms the Family Offices Market is expanding at a 6.64% CAGR, scaling from 23.71 Billion in 2026 to 37.19 Billion by 2033. This growth reflects institutionalization, professionalization of staff, and sophisticated diversification into non-traditional asset classes.
Market forecast from 2027 to 2033
Driven by compounding generational wealth and expanding private market access, the market is projected to surge to 37.19 Billion by 2033 at a steady 6.64% CAGR. Investment offices will capture the lion's share of this expansion as liquidity events generate unprecedented new pools of investable capital.
Segmentation analysis by type, office, asset class, and net-worth
Segmentation breaks down by Type (Single, Multi-Family, Virtual), Office (Founders, Compliance, Philanthropy, Investment, etc.), Asset Class (Bonds, Equities, Alternatives, Commodities, Cash), and Net-Worth Managed (Under 50M, 50M-100M, Over 100M). Alternative investments and multi-family structures lead current expansion metrics.
Regional market analysis and geographic distribution
Geographic performance highlights North America as the dominant revenue generator, anchored by robust tech wealth generation. Europe follows closely, driven by mature multi-family offices in Switzerland and the UK, while Asia-Pacific emerges as the fastest-growing region fueled by new billionaire creation in financial hubs.
In-depth regional review of key markets
North America benefits from a dense concentration of founders' offices managing hyper-growth venture assets. Simultaneously, European jurisdictions emphasize wealth preservation under complex EU tax frameworks, while Asia-Pacific family offices increasingly institutionalize cross-border investments into Western technology sectors.
Company profiles and strategic positioning of leading firms
Prominent entities like Cascade Investment Group Inc. and Soros Fund Management LLC utilize highly concentrated, thesis-driven equity strategies. Meanwhile, wealth managers like Northern Trust Corporation and Citigroup Inc. provide scalable multi-family operational backbones, capturing mid-tier ultra-high-net-worth client flows.
Porter's Five Forces analysis of competitive intensity
Bargaining power of clients is high due to bespoke service demands, while threat of new entrants remains moderate given steep regulatory and compliance barriers. Rivalry among established players like Rockefeller Capital Management L.P. and BMO Financial Group intensifies around talent acquisition and proprietary deal flow access.
SWOT analysis of the Family Offices Market
Key strengths include deep liquidity pools and long-term investment horizons. Weaknesses involve high operational overheads and succession planning friction. Opportunities exist in fractionalized alternative assets, whereas regulatory crackdowns on cross-border tax optimization pose significant ongoing threats.
Value chain analysis from origination to end-users
The value chain originates with primary wealth creation events, flowing through legal structuring and tax advisory, down to asset allocation and execution. Specialized players like The Raine Group LLC and Tiger Global Management LLC sit mid-chain, providing crucial direct private market deal access to family investment vehicles.
Investment insights and high-potential areas
Strategic recommendations emphasize allocating capital toward technology-enabled virtual family office platforms and secondary private equity funds. Our analysis indicates that firms investing in automated regulatory compliance and cybersecurity infrastructure will capture outsized operational efficiency gains.
Conclusion and key takeaways for stakeholders
The Family Offices Market represents a vital pillar of global capital allocation. With a projected valuation of 37.19 Billion by 2033, stakeholders must embrace digital transformation, professionalized governance, and alternative asset diversification to maintain competitive advantage in an increasingly regulated landscape.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by synthesizing proprietary trade registry data, structured primary interviews with chief investment officers, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of opaque private wealth segments across global markets.
Scope of the report and coverage parameters
This report covers global family office structures managing assets across single, multi-family, and virtual configurations. Limitations exclude informal, unrecorded private wealth holdings below the 50 Million threshold, focusing strictly on institutionalized wealth management entities and formal investment offices.
Recent developments in the ecosystem
Recent strategic moves feature increased cross-border joint ventures and technology acquisitions. Firms like ICONIQ Capital LLC and Hillhouse Capital Management Limited have expanded their private equity syndication networks, partnering with global banks to secure exclusive late-stage venture allocations.